A New Way to Qualify: What the Fannie Mae and Freddie Mac Credit Score Update Means for Homebuyers
New credit scoring update could save you time, lower your costs, and open doors to a better home loan approval.
A New Way to Qualify: What the Fannie Mae and Freddie Mac Credit Score Update Means for Homebuyers
When you are shopping for a home, every single detail on your credit report and credit score matters. For years, the mortgage industry has relied almost exclusively on a single traditional scoring model to evaluate whether you qualify for a conventional loan.
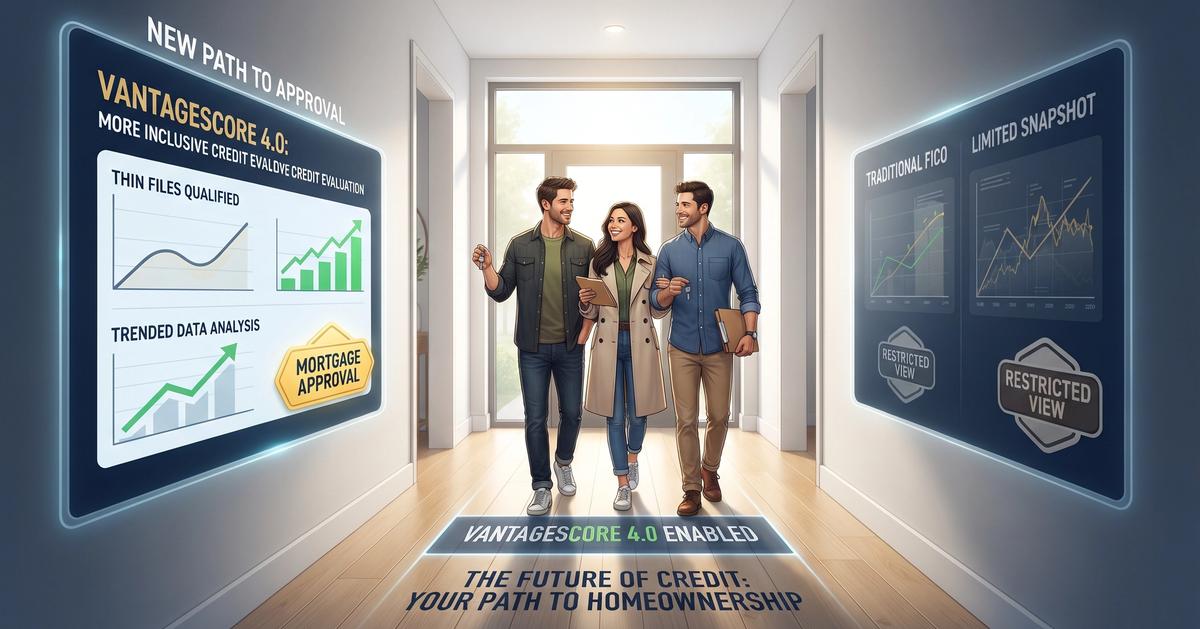
That standard is officially expanding. On September 9, 2026, Fannie Mae and Freddie Mac (the GSEs) opened VantageScore 4.0 to all approved lenders, converting what started as a limited rollout into a wide-open option for conventional loans.
If you have ever worried that traditional credit scoring models don't tell your complete financial story—especially if you have a thin credit file or are working hard to build strong financial habits—this shift could be a game-changer for your homebuying journey.
1. What is VantageScore 4.0, and Why Does It Matter for Buyers?
For decades, the mortgage market has run on older credit scoring models. VantageScore 4.0 is a modern credit scoring model designed to evaluate credit usage and history more accurately and inclusively.
- More Inclusive Scoring: It incorporates trended data (looking at how you manage credit over time rather than just a single snapshot) and can successfully score millions of consumers who might otherwise be considered "unscorable" under older frameworks.
- Potential for Better Pricing and Approvals: By offering a more accurate reflection of modern financial behavior, a new scoring model can sometimes open doors to approvals or better terms that might have been bottlenecked under strict, legacy guidelines.
2. How This Can Save You Time, Money, and Stress
While this update is technically rolling out through lenders and automated underwriting systems behind the scenes, the potential consumer benefits are significant:
- A Path for "Thin" Files: If you haven’t relied heavily on traditional credit cards in the past but have a pristine history of paying rent, utilities, and telecom bills on time, modern scoring models are much better at recognizing that positive track record.
- Potential Rate and Cost Savings: Qualifying under a model that captures a more comprehensive picture of your financial responsibility could help optimize your risk profile, potentially unlocking more favorable loan terms or reducing out-of-pocket costs.
- More Flexibility: Because lenders now have the green light to utilize this model alongside traditional FICO for automated underwriting, your loan originator has more tools in their toolkit to find a qualification path that fits your unique profile.
3. What Stays the Same on Your Loan Application?
While credit models are evolving, the baseline security and structure of the mortgage process remain strong and predictable:
- Comprehensive Tri-Merge Reports: Lenders will still pull a standard tri-merge credit report gathering data from all three major national credit bureaus (Equifax, Experian, and TransUnion).
- Loan File Consistency: Your lender will ensure that whichever scoring model is chosen for your application is used consistently across every borrower on that specific loan file.
- Government Programs: While conventional loans backed by Fannie Mae and Freddie Mac are adopting this option, other programs like FHA have not yet transitioned to VantageScore 4.0, meaning traditional guidelines still apply there.
The Bottom Line: Talk to a Professional Who Understands Modern Options
Navigating mortgage approvals isn't just about plugging numbers into a computer—it’s about working with a knowledgeable advocate who knows how to evaluate your entire financial picture to find the best execution, lowest fees, and smoothest path to the closing table.
Curious about how your credit profile stacks up or want a transparent review of your options before you start house-hunting? Reach out today for a zero-obligation consultation.
Addison Nett
Independent Mortgage Broker & Loan Originator | NMLS #1542184
Licensed in: AZ, ID, OR, WA, TX 📍
NEXA Mortgage LLC
📞 971-263-8140
✉️ anett@nexamortgage.com | AZ BANKER license number: BK-2006218
NEXA Mortgage | #1660690 | AZMB # 0944059
Equal Housing Opportunity
© 2026 NEXA Mortgage, LLC. NMLS #1660690 • AZBK-2006218 • Equal Housing Lender.