The Hidden Cost of Retail Mortgage Pricing (and How Brokers Beat It)
Learn the hidden costs of retail mortgage lending and how the LEAN wholesale broker model delivers lower rates, zero junk fees, and faster closings.
The Hidden Cost of Retail Mortgage Pricing (and How Brokers Beat It)
When you walk into a traditional retail bank or call a massive call-center lender, it’s easy to assume you’re getting the most direct and competitive deal. But after spending a decade working inside the retail mortgage machine, I saw firsthand where the money actually goes—and it’s not into your savings.
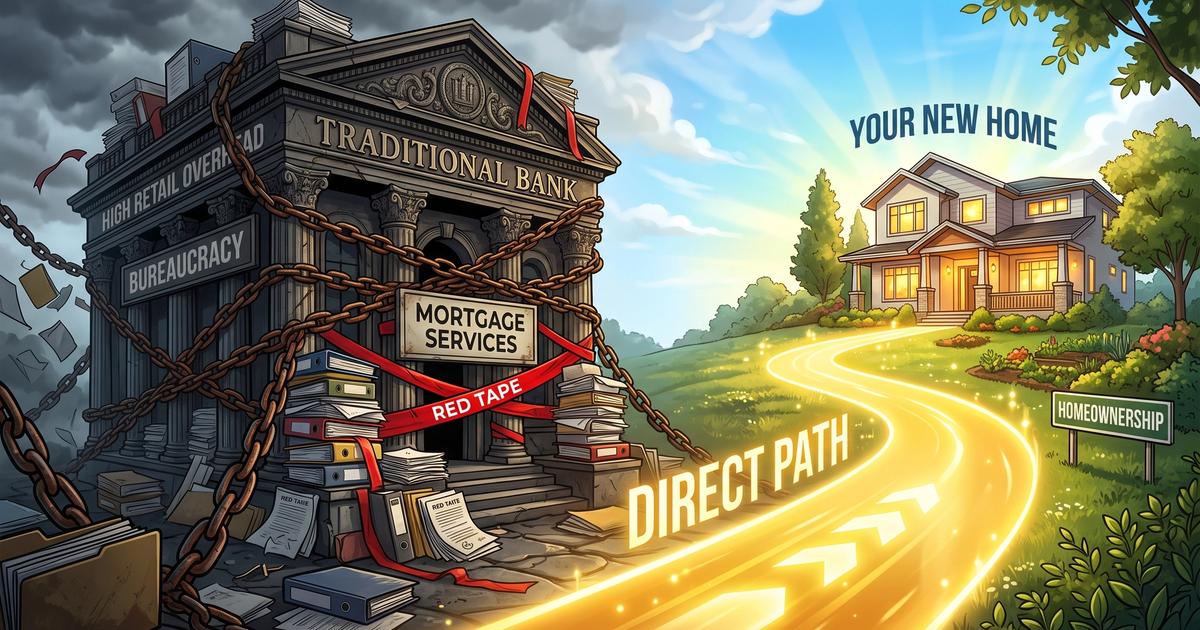
The traditional retail banking model is weighed down by structural inefficiencies that force them to charge higher interest rates and pad their loans with extra fees. By contrast, an independent wholesale mortgage broker strips away the corporate bureaucracy.
As a dedicated mortgage broker utilizing a LEAN operational model, my practice is built around wholesale pricing, zero junk fees, and direct execution. Here is why the wholesale broker advantage consistently beats the retail banking model.
1. The Hidden Overhead of "Direct" Retail Lenders The biggest secret in the mortgage industry is that you aren't just paying for your house; when you use a retail lender, you are paying for their corporate infrastructure.
- The "Direct Lender" Mirage: Many large national mortgage companies market themselves heavily as "direct lenders" or "independent mortgage banks," suggesting that working directly with their brand saves you money. But "direct" simply means retail. Origination benchmarking consistently reveals that retail branch operations incur massive corporate overhead—averaging over $10,000 to $16,000 per loan—covering physical branch leases, regional management overrides, and national TV advertising campaigns.
- Who Pays the Overhead? A retail company cannot absorb multi-million-dollar operational footprints on its own. That overhead is built directly into the consumer's interest rate and closing fees.
2. Captive Rate Sheets vs. True Wholesale Access When a retail loan officer tells you they have a great rate, they mean they have a great rate for their specific company.
- The In-House Bottleneck: Whether it's a legacy mega-bank or a national non-bank retail lender, their loan officers are tied to a single captive pricing sheet. If their company's profit margins or underwriting capacity dictate higher pricing this week, they cannot shop elsewhere for you.
- The Wholesale Solution: As an independent broker, I don't work for a single retail lender. I tap directly into an open exchange, forcing top wholesale institutions to compete for your business on raw price and lean margins.
3. Zero Junk Fees and Pure Pricing A "low rate" advertised by a retail lender often hides thousands of dollars in profit baked into the fine print.
- The Loan Estimate Padding: Retail and correspondent lenders do not have to disclose their total profit margin, allowing them to hide costs in higher rates or upfront origination charges.
- The LEAN Advantage: My independent business model is built on ruthless efficiency. By operating without dedicated processors or loan officer assistants, I eliminate operational friction. That translates to zero junk fees on your Loan Estimate and true, bottom-line savings when you bring your cash to close.
4. Direct Communication & Elite Execution In a traditional retail environment, your file is passed down an assembly line. You speak to the loan officer to apply, but then you are handed off to a processing team, an assistant, and a disconnected closing department.
- Your Single Point of Contact: In a traditional retail environment, you may experience slower turn times because your file is passed through various internal departments and queues. With my LEAN workflow, I am your direct partner from the initial pre-approval all the way through funding. You have my direct line via call, text, or email.
- Speed to Close: Because I personally manage the technical workflow and underwriting systems without waiting on a corporate assembly line, I average 10 to 12-day clear-to-closes, ensuring you never miss a deadline.
Ready to Experience the Wholesale Difference? If you are tired of corporate bureaucracy and want a mortgage partner who leverages wholesale pricing, operates with zero junk fees, and delivers elite execution, let’s connect. Reach out today to see how much you can save when you bypass the retail markup.
Addison Nett Mortgage Loan Officer | NMLS #1542184 Licensed in AZ, ID, OR, WA, TX 📍 NEXA Mortgage LLC 📞 971-263-8140 ✉️ anett@nexamortgage.com | AZ BANKER license number: BK-2006218 NEXA Mortgage | #1660690 | AZMB # 0944059 Equal Housing Opportunity © 2026 NEXA Mortgage, LLC. NMLS #1660690 • AZBK-2006218 • Equal Housing Lender. https://nexamortgage.com/disclaimer/ https://www.nmlsconsumeraccess.org/